Buy With The Knoedler Team

Expert guidance, market insights, and seamless support to help you find the right home.

How we help you buy

Finding the right property is only one part of buying a home. Understanding its value, identifying potential concerns, and negotiating the right terms are just as important.

At the Knoedler Team, we help our buyers evaluate properties using recent comparable sales, local market conditions, and a thorough review of the information available. From arranging showings and reviewing strata documents to negotiating offers and coordinating inspections, we're involved throughout the entirety of the process.

Our goal is simple: to help you understand what you're buying, what it's worth, and what to expect before making a commitment.

first time buyer?

Buying your first home comes with plenty of questions, but there are also several government programs designed to make homeownership more affordable. From property transfer tax exemptions and GST rebates to tax credits and savings programs, eligible first-time buyers in BC may be able to save thousands of dollars. We've put together a guide outlining the benefits available, how they work, and who may qualify.

Explore our First Time Buyer's Guide

your home buying roadmap

A simple guide to what happens between your first showing and getting the keys.

01    GET PREAPPROVED   |   Before you start looking


Speak with a mortgage broker or lender about your budget, down payment, monthly costs and financing options. A preapproval is not a final mortgage approval.


02    FIND THE RIGHT PROPERTY   |   As long as you need


We set up a MLS search, tour homes, evaluate recent comparable sales and investigate the details that matter to you.


03    WRITE & NEGOTIATE AN OFFER   |   Often 1–3 days; varies


We prepare a Contract of Purchase and Sale specifying the price, deposit, included items, completion and possession dates, and any subject conditions. An accepted offer is a binding contract, subject to its terms.


04    COMPLETE YOUR SUBJECT PERIOD   |   Often 5–10 business days; negotiated


Where included in your contract, this is the time to arrange an inspection, obtain satisfactory financing, review strata documents, confirm insurance and complete other agreed due diligence. Every subject has its own deadline.


05    REMOVE SUBJECTS & PAY THE DEPOSIT   |   As specified in your contract


Once satisfied, you can remove your subjects in writing. The deposit is paid on the date your contract requires, often upon or shortly after subject removal. It is generally held in our brokerage trust account and credited toward your purchase funds.


06    MEET YOUR LAWYER OR NOTARY   |   Usually shortly before completion


Your lender and conveyancer prepare the closing paperwork. You arrange the remaining down payment and closing costs, and sign the transfer and mortgage documents.


07    COMPLETION, THEN POSSESSION   |   Dates in your contract


On completion, ownership is legally transferred and funds are paid. On the possession date, you are entitled to the keys and can move in. These dates may be different but are typically 1-3 days apart.

TWO IMPORTANT THINGS TO KNOW

BC’s Home Buyer Rescission Period. For most eligible resale homes, you have three business days after acceptance to rescind in writing, with a 0.25% fee based on the purchase price. Some property types and transactions are exempt. This is separate from negotiated subjects.

Subject removal is a major commitment. Once your subjects are removed, the transaction will generally be unconditional. An existing accepted offer is already a binding contract; always discuss the conditions and deadlines with us before taking action.

BUDGET FOR CLOSING COSTS

In addition to your down payment, allow for applicable Property Transfer Tax and GST, legal/notary fees, inspection, insurance, adjustments and moving expenses.

understanding subject conditions

A practical guide to the checks you can make before committing to a purchase

Subject conditions are negotiated protections written into an offer. They give you time to investigate specific matters before proceeding. Not every offer includes every subject, and each has its own deadline.


01 FINANCING |
Mortgage approval


Your lender must approve both you and the specific property. A mortgage preapproval is not final approval; an appraisal and other lender requirements may still apply.


02    HOME INSPECTION   |   Property condition


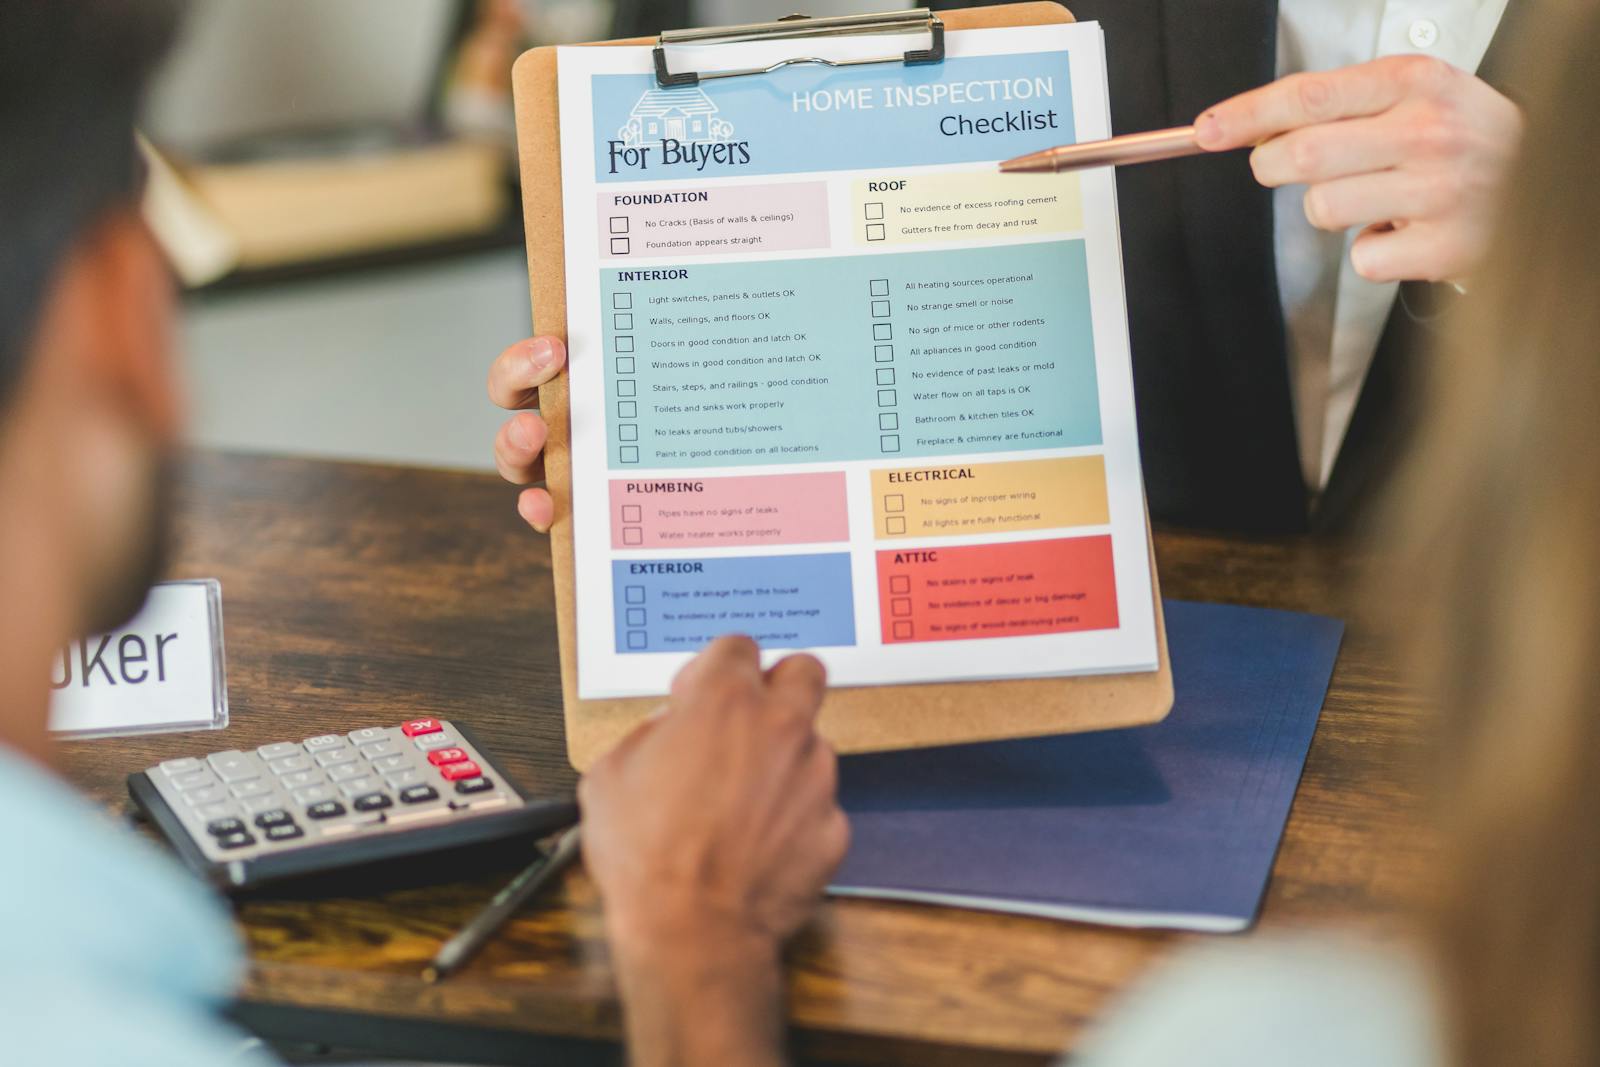
Have a qualified inspector assess the home. For older properties, we may also recommend specialist checks for drainage, moisture, electrical issues or buried oil tanks, or pools if applicable.


03    STRATA DOCUMENTS   |   Condos & strata townhomes


Review the Form B, minutes, financial statements, budgets, bylaws, insurance and depreciation or engineering reports. Watch for special levies, planned work, insurance deductibles and parking/storage arrangements.


04    INSURANCE   |   Coverage and cost


Confirm with your broker that suitable insurance is available at an acceptable cost. Ask about concerns such as previous water damage, older building systems or special coverage needs; strata owners usually need their own policy too.


05    DISCLOSURE & TITLE   |   Property information


Review the seller's Property Disclosure Statement for any noted defects and the title search for registered charges, easements or covenants. Check permits, suites or other property-use questions when they matter to your plans.


06    SALE OF YOUR HOME   |   If applicable


If you need to sell first, you may negotiate a subject-to-sale condition. Most contracts include a time clause that allows the seller to keep marketing the property to other buyers.
If the seller receives a better, unconditional offer, the time clause triggers a countdown (usually 24 to 72 hours). The original buyer must then either: Waive their conditions and commit to buying the property immediately or walk away, allowing the seller to accept the new offer.

 
WHAT HAPPENS DURING THE SUBJECT PERIOD?


1. An accepted offer is binding. Subject periods are often around 5–10 business days, but your contract sets the actual dates and times. We help coordinate the process; you must make reasonable, good-faith efforts to meet each condition.
2. Decide before the deadline. Once satisfied, you remove your subjects in writing. If a condition genuinely cannot be met, speak with us promptly. Subjects are not a general right to change your mind.
3. Subject removal is a commitment. Once all subjects are removed, the purchase is generally unconditional. The deposit –typically 5% of the purchase price- is due when your contract says, often upon or shortly after removal. Deposits held in trust are not always automatically released if a deal ends.


THE BC RESCISSION PERIOD IS SEPARATE


For most eligible residential purchases, BC provides a three-business-day right to rescind after offer acceptance, with a fee of 0.25% of the purchase price. It runs at the same time as your subject period. Certain purchases, including leasehold/leased-land properties, are excluded.


Removing subjects before completing your checks, or making a subject-free offer, can expose you to major financial risk. Ask us questions before committing.


Understanding Strata Documents

A practical guide to reviewing an attached home's documents

With a strata home, you share the building's maintenance costs, insurance and future repairs. The documents help us understand the strata's financial health, building condition and possible expenses beyond your monthly fee.


01    FORM B   |   The property snapshot


Shows current strata fees, reserve funds, approved special levies and payment dates, insurance summary, legal proceedings, and parking or locker details. Read the attachments; no approved levy does not mean no future levy.


02    MINUTES & BYLAWS   |   History and rules


Review council, AGM and special meeting minutes for leaks, recurring repairs, engineering work, disputes, proposed projects or fee increases. Check bylaws for pets, renovations, rentals and other restrictions that affect your plans.


03    BUDGET & RESERVE FUND   |   Financial health


Monthly fees pay ongoing costs, including the strata's annual insurance premium. The contingency reserve fund (CRF) is for less frequent major expenses. Compare savings, deficits and contributions against the building's upcoming work.


04    DEPRECIATION & ENGINEERING REPORTS   |   Building Health and Future


A depreciation report forecasts major repair and replacement costs over 30 years; it is not a detailed technical inspection. Engineering reports investigate specific concerns such as structural, moisture or building-envelope deficiencies.


05    SPECIAL LEVIES   |   Extra payments beyond strata fees


A special levy raises money for a specific expense. Check this unit's share, due dates and the work being funded. Proposed levies may appear in minutes before approval. The seller is typically responsible for levies approved before a sale, with the details being outlined in the contract.


06    INSURANCE & DEDUCTIBLES   |   Know both numbers


The annual insurance premium affects strata fees; the deductible is the amount paid toward a claim. Water-damage deductibles can reach six figures. If responsible for a loss, an owner may face deductible recovery even without negligence. Confirm suitable personal strata insurance with a broker.


07    PARKING, STORAGE & RESPONSIBILITIES   |   Confirm what is included


Verify the parking and locker numbers and whether rights are owned, limited common property or assigned. Check repair responsibilities for balconies, windows, patios, alterations and other common or limited-common areas.


BIG-TICKET BUILDING ITEMS WE WATCH


Building envelope & windows.  Waterproofing, cladding, flashing and sealants; past or ongoing water entry can lead to major remediation.
Podium / parkade membrane.  Waterproofing beneath a courtyard, landscaping or patio over a parkade; repairs may mean removing surfaces above it.
Roof, balconies & decks.  Ageing membranes, drainage, railings and recurring leaks can require extensive replacement.
Piping, mechanical & elevators.  Repiping, drainage, boilers, HVAC, elevators and fire-safety systems can be major shared costs.


QUESTIONS TO ASK BEFORE REMOVING SUBJECTS


What work is recommended or being investigated? Is the scope priced and funded? Have major repairs been delayed? What is this unit's potential share of upcoming costs? Are insurance premiums and deductibles manageable, and can you obtain appropriate owner coverage?
A planned repair is not automatically a red flag. The key is whether the strata understands the issue, has reliable advice and a realistic funding plan.

Reciprocity Logo The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.